Showing posts with label Implicit/Explicit Gov Guarantees. Show all posts

Friday, June 12, 2009

This is not just theory; it is a lesson we learned, at great expense, during the Savings and Loan crisis of the 1980s

TO BE NOTED: From The Guardian:

"
America's socialism for the rich

The US has a huge corporate safety net, allowing the banks to gamble with impunity, but offers little to struggling individuals

With all the talk of "green shoots" of economic recovery, America's banks are pushing back on efforts to regulate them. While politicians talk about their commitment to regulatory reform to prevent a recurrence of the crisis, this is one area where the devil really is in the details – and the banks will muster what muscle they have left to ensure that they have ample room to continue as they have in the past.

The old system worked well for the bankers (if not for their shareholders), so why should they embrace change? Indeed, the efforts to rescue them devoted so little thought to the kind of post-crisis financial system we want that we will end up with a banking system that is less competitive, with the large banks that were too big too fail even larger.

It has long been recognised that those America's banks that are too big to fail are also too big to be managed. That is one reason that the performance of several of them has been so dismal. Because government provides deposit insurance, it plays a large role in restructuring (unlike other sectors). Normally, when a bank fails, the government engineers a financial restructuring; if it has to put in money, it, of course, gains a stake in the future. Officials know that if they wait too long, zombie or near zombie banks – with little or no net worth, but treated as if they were viable institutions – are likely to "gamble on resurrection". If they take big bets and win, they walk away with the proceeds; if they fail, the government picks up the tab.

This is not just theory; it is a lesson we learned, at great expense, during the Savings and Loan crisis of the 1980s. When the ATM machine says "insufficient funds", the government doesn't want this to mean that the bank, rather than your account, is out of money, so it intervenes before the till is empty. In a financial restructuring, shareholders typically get wiped out, and bondholders become the new shareholders. Sometimes the government must provide additional funds; sometimes it looks for a new investor to take over the failed bank.

The Obama administration has, however, introduced a new concept: too big to be financially restructured. The administration argues that all hell would break loose if we tried to play by the usual rules with these big banks. Markets would panic. So, we not only can't touch the bondholders, we also can't even touch the shareholders – even if most of the shares' existing value merely reflects a bet on a government bailout.

I think this judgment is wrong. I think the Obama administration has succumbed to political pressure and scaremongering by the big banks. As a result, the administration has confused bailing out the bankers and their shareholders with bailing out the banks.

Restructuring gives banks a chance for a new start: new potential investors (whether in equity or debt instruments) will have more confidence, other banks will be more willing to lend to them and they will be more willing to lend to others. The bondholders will gain from an orderly restructuring, and if the value of the assets is truly greater than the market (and outside analysts) believe, they will eventually reap the gains.

But what is clear is that the Obama strategy's current and future costs are very high – and so far, it has not achieved its limited objective of restarting lending. The taxpayer has had to pony up billions, and has provided billions more in guarantees – bills that are likely to come due in the future.

Rewriting the rules of the market economy – in a way that has benefited those that have caused so much pain to the entire global economy – is worse than financially costly. Most Americans view it as grossly unjust, especially after they saw the banks divert the billions intended to enable them to revive lending to payments of outsized bonuses and dividends. Tearing up the social contract is something that should not be done lightly.

But this new form of ersatz capitalism, in which losses are socialised and profits privatised, is doomed to failure. Incentives are distorted. There is no market discipline. The too-big-to-be-restructured banks know that they can gamble with impunity – and, with the Federal Reserve making funds available at near-zero interest rates, there are ample funds to do so.

Some have called this new economic regime "socialism with American characteristics". But socialism is concerned about ordinary individuals. By contrast, the US has provided little help for the millions of Americans who are losing their homes. Workers who lose their jobs receive only 39 weeks of limited unemployment benefits, and are then left on their own. And, when they lose their jobs, most lose their health insurance too.

America has expanded its corporate safety net in unprecedented ways, from commercial banks to investment banks, then to insurance and now to cars, with no end in sight. In truth, this is not socialism, but an extension of longstanding corporate welfarism. The rich and powerful turn to the government to help them whenever they can, while needy individuals get little social protection.

We need to break up the too-big-to-fail banks; there is no evidence that these behemoths deliver societal benefits that are commensurate with the costs they have imposed on others. And, if we don't break them up, then we have to severely limit what they do. They can't be allowed to do what they did in the past – gamble at others' expenses.

This raises another problem with America's too-big-to-fail, too-big-to-be-restructured banks: they are too politically powerful. Their lobbying efforts worked well, first to deregulate and then to have taxpayers pay for the cleanup. Their hope is that it will work once again to keep them free to do as they please, regardless of the risks for taxpayers and the economy. We cannot afford to let that happen.

Copyright: Project Syndicate, 2009"

Wednesday, June 10, 2009

Fed operated when it rescued Bear Stearns, the market then believed this was a signal of the way the Federal Reserve would perform

TO BE NOTED:

Taking Stock: Lessons from history Economist Anna Schwartz

Revered economist and monetary policy expert Dr. Anna Schwartz talks with Kai Ryssdal about how the Federal Reserve and government have performed while in the economic hot seat. She isn't too pleased.

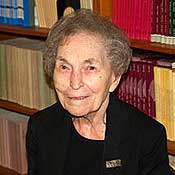
Economist Anna Schwartz (silverbearcafe.com)

More on America's Financial Crisis

TEXT OF INTERVIEW

Kai Ryssdal: Today we're going to pick up with our series Taking Stock, occasional conversations with people who can give us the long view of our current economic situation.

There aren't many people around today who can give us that perspective better than Anna Schwartz. She's 93 years old, an economist for more than 60 of them. Still working, every day, at the National Bureau of Economic Research in New York City. Her area of expertise is monetary policy, how much money is in the economy, usually controlled by the interest rates that the Federal Reserve sets. Specifically, she's an expert in how the Fed blew it during the Great Depression, when customer after customer pulled their money out of the banks.

ANNA SCHWARTZ: The Federal Reserve could easily have provided additional money supply. That would have helped the banks that were losing deposits and that would have helped the economy in general.

Forty-six years ago Schwartz, and a guy named Milton Friedman, who'd later go on to win the Nobel Prize for economics, wrote a book on the topic. It was called "A Monetary History of the United States." It's on just about every list of the most important books on economic history... ever. When I sat down with her in her office in Manhattan last month, she made it clear she's none too happy about all of Washington's bailouts, or how the Fed and the Treasury chose who got one and who didn't.

Schwartz: I think both Bush and the Obama administration have not been as hard headed with banks, it has been too lax. And instead if they had said if you cannot raise capital in the market, there is no reason for the government, the people of this country, to provide capital.

Ryssdal: OK, but wait a minute. Didn't we try that with Lehman Brothers last September? And there are people who will say that only made everything worse. Should we now say to Bank of America, and Citigroup and some of these other banks, "Hey, you can't make your loans..."

SCHWARTZ: No, the trouble with the way the Fed operated when it rescued Bear Stearns, the market then believed this was a signal of the way the Federal Reserve would perform. If the Fed and the Treasury made a candid statement to the market: We will help a bank, which basically is solvent. We will not do that for a bank, which is on the verge of bankruptcy. And then the market understands there are principles. That's why when Lehman Brothers was permitted to fail, the market was simply bewildered. Because here you had treated Bear Stearns in this kindly fashion, and what reason was there not to do the same when Lehman Brothers arose?

Ryssdal: Now do you think the market has figured out what the policy of the federal government is toward these rescues by now? It's been six, seven months since Lehman Brothers.

SCHWARTZ: The market is just bewildered. Bernanke came into office insisting that the Fed would be much more transparent than it had been in the past. But I don't believe that it's lived up to that. If the market understood what the Fed was planning in each case, and could see a design, then I think the market would have reacted much more positively.

Ryssdal: It sounds like you're frustrated with Chairman Bernanke and the White House, that they maybe haven't learned the lessons of history that you and Milton Friedman wrote about.

SCHWARTZ: Well, I think that that's a fair statement. Considering Bernanke's background, you would have expected a much more, should I say a tidy kind of performance by the Federal Reserve. Seemed to be something that was ad hoc and introduced without considering all the implications.

Ryssdal: You know, Alan Greenspan was lionized in this country for many years. And then a year ago went up to Capitol Hill and said, "You know what, I blew it." Does he get the appropriate amount of credit and/or blame for this whole thing?

SCHWARTZ: Well, I think the verdict of history will be different with regard to his stature than it has been so far.

Ryssdal: In your mind, these toxic assets, the bad assets that these banks still have on their books, are they still a big problem or have they worked their way through the system now?

SCHWARTZ: No, and I think the big shortcoming of the Obama administration, and Bush before that, was that it didn't make a concerted effort to get rid of these assets. I mean in a sense it's a condemnation of the Federal Reserve. They did not respond to securitization, which is the basic condition for the creation of these toxic assets. Neither Alan Greenspan or anybody else at the Fed seemed to be concerned.

Ryssdal: Securitization, that is the buying and selling of these packages of mortgages. There are those who will say it contributed a lot to the economic growth in this country. Do you buy that?

SCHWARTZ: Well, I suppose the people who made money on it will say, Sure. But you have to be able to divine what you're letting yourself in for, if you're going to permit securitization to go on. And nobody took action to say, "Wait a minute. What are we doing when we are permitting these mortgage companies to issue these securities backed by a pool of mortgages of varying quality, and you don't know how to price the security?" Nobody raised that question.

Ryssdal: When an economic historian comes along in 25 or 30 years and tries to do for this episode what you and Professor Friedman did for the Great Depression, what's their verdict going to be on the monetary policy that the Fed has been following?

SCHWARTZ: Well, there has not been a straight line in the programs that the Fed has introduced over this period. So, I don't know whether the verdict will be charitable. It's always possible to find reasons why other alternatives were not really available. But I think on the whole the performance has been disappointing. Because now two years and more after Bernanke came into office we don't see visible signs of change for the better.

Ryssdal: Dr. Anna Schwartz. She's an economist with the National Bureau of Economic Research, has been since 1941. She's also the co-author, with Milton Friedman, of "A Monetary History of the United States."

Thursday, June 4, 2009

if the economy gets worse and they ever need to unload those loans, they can count on the plan being resurrected

From The Baseline Scenario:

"Legacy Loan Program Called Off

with 17 comments

New York Times:

The Federal Deposit Insurance Corporation indefinitely postponed a central element of the Obama administration’s bank rescue plan on Wednesday, acknowledging that it could not persuade enough banks to sell off their bad assets. . . .

Many banks have refused to sell their loans, in part because doing so would force them to mark down the value of those loans and book big losses. Even though the government was prepared to prop up prices by offering cheap financing to investors, the prices that banks were demanding have remained far higher than the prices that investors were willing to pay.

I don’t think I’ve ever done this before, but . . . Simon and I, March 24:

The problem in the market today is that the prices demanded by the banks are much higher than the prices that private buyers (hedge funds, private equity firms, sovereign wealth funds) are willing to pay. The government has no way to bring down the banks’ minimum sale prices . . .

The subsidy may not be sweet enough to close the deal. According to one analysis, a specific mortgage-backed security was held on a bank’s books at 97 cents, while its market price was about 38 cents. Even if you limit the buyer’s potential loss to the capital he put in, it’s unlikely he will raise his bid from 38 cents to anything near 97 cents. . . .

Just last week at least some banks wanted to participate in the program – to buy assets from themselves. Once Sheila Bair rejected that idea, I guess they lost interest. Essentially the stress tests placed a big government stamp of approval on their balance sheets, so their current strategy is to wait out the recession and hope the prices of their legacy loans recover. There’s no downside risk, because if the economy gets worse and they ever need to unload those loans, they can count on the plan being resurrected.

I guess we were, however, wrong to worry about inter-bank collusion in the legacy loans program.

(Note that this does not apply to the legacy securities program, which may still be going ahead.)

By James Kwak"

Me:

“Essentially the stress tests placed a big government stamp of approval on their balance sheets, so their current strategy is to wait out the recession and hope the prices of their legacy loans recover. There’s no downside risk, because if the economy gets worse and they ever need to unload those loans, they can count on the plan being resurrected.”

You are correct. However, the problem is also on the buy end. After all, if the sellers could get their asking price, then they’d sell. Without a Subsidy to buy these assets, balancing the implicit subsidy of government guarantees, no reasonable person would buy these assets. It’s also very true that one can imagine a tax introduced later to get the subsidy back, which is the buyer’s big vocal complaint.

The big problem is that, now, these assets aren’t distressed enough, compared to other investments. In other words, the buyers can afford to be patient as well. We’re back to where we were before.

Tuesday, June 2, 2009

Geithner went out of his way to assure the Chinese that their large holdings of US dollar assets were secure

TO BE NOTED: From the FT:

"
Geithner says China backs US stimulus

By Kathrin Hille in Beijing

Published: June 2 2009 19:50 | Last updated: June 2 2009 19:50

China has expressed confidence in the US economy and the Obama administration’s policies on fighting the recession, the US Treasury secretary said on Tuesday.

Speaking on the second day of a closely watched visit to Beijing, Tim Geithner said there was “a very sophisticated understanding” in China about why the US needs to run large budget deficits in the short term, although he repeated the pledge to sharply reduce deficits when the crisis is over.

“I sense . . . a fair amount of confidence not just in the basic underlying strength of the US economy but in our capacity not just to solve this crisis, to get growth back on track, but to go back to living within our means,” Mr Geithner told reporters.

During the visit, his first to Beijing as Treasury secretary, Mr Geithner went out of his way to assure the Chinese that their large holdings of US dollar assets were secure and that the administration remained committed to a strong dollar and keeping inflation under control.

In recent months, Chinese leaders have issued a string of warnings about the risks that the US will inflate away its mounting debt burden.

Although Chinese officials did not bring up the issue again in public during the visit, there were plenty of other signs of concern, including the tough questioning Mr Geithner received from students after giving a speech at Peking University.

Mr Geithner said that his confidence in the US dollar was shared by Beijing. “I believe the Chinese expect the dollar to be the principal reserve currency for a long period of time, as do we,” he said.

As Mr Geithner wrapped up his visit, Beijing and Washington announced plans to start their “strategic and economic dialogue” – the Obama administration’s renamed version of bilateral consultations – in Washington in late July.

The discussions next month would give both sides the opportunity to explore each others’ policies in more detail.

“We’re going to have lots of time to talk to them about the specific content of their reform agenda, just like they’re going to want to talk to us about ours,” he said.

Mr Geithner said the two countries had already demonstrated they could co-operate in laying a foundation for economic recovery. “I think probably because of the actions put in place by your government and by President Obama, we are starting to see some early signs of stabilisation and recovery in the global economy,” he said in a meeting with Hu Jintao, China’s president.

Mr Hu said the visit by Mr Geithner, who irritated Beijing when he said during his confirmation hearing that China “manipulated” its currency, had helped improve co-operation between the two countries.

destabilised financial system to a more solid system with more modest systemic guarantees where even “too big to fail” firms are allowed to fail

From the FT:

"
US crisis: the role of systemic risk guarantees

June 2, 2009 11:46am

By Carolyn Sissoko

US Federal Reserve

US Federal Reserve

In recent years many large financial institutions have become used to the idea that governments stand ready to rescue the financial system when it gets into trouble. Swift regulatory intervention in the US whenever there was a systemic event encouraged this view. Over time, confidence in the government’s ability to act as the financial system’s executive manager resulted in a transfer of the responsibility for controlling systemic risk from the banks to the government.

In the early years of the 20th century, there was no central bank; systemic risk was resolved by the coordinated action of the banks through clearinghouses. While the founding of the Federal Reserve in 1913 might have transferred the responsibility for systemic risk away from the banks themselves, the Fed’s behaviour during the 1930s did not lend credence to this view. The systemic risks of the Great Depression were addressed by policymakers in Washington after Franklin D. Roosevelt became president, not by the central bank.

Experiences such as the Great Depression leave scars. For decades after, banks were managed with the understanding that, while the Federal Deposit Insurance Corporation would save their depositors, the banks themselves would in all likelihood be allowed to fail in the event of a systemic crisis.

In 1984, the implicit expansion of the federal safety net to include the creditors of “too big to fail” banks took place when the FDIC’s resolution of Continental Illinois protected the bondholders of the holding company. Continental Illinois was seized in 1984 in a move that was, at the time, the largest bank restructuring undertaken by the US.

Then in 1987 when the stock market crash left some of the investment banks with too little collateral to back their financing needs, the New York Federal Reserve Bank president intervened to protect them. In 1991 Congress condoned this expansion of the federal safety net by revising the Federal Reserve Act to enable the Fed to lend in an emergency against the collateral held by investment banks - or even hedge funds.

In a speech in February 1998, Alan Greenspan, then Fed chairman, made the new role of the central bank explicit by stating: “The management of systemic risk is properly the job of the central banks. Individual banks should not be required to hold capital against the possibility of overall financial breakdown. Indeed, central banks, by their existence, appropriately offer a form of catastrophe insurance to banks against such events.”

In short, over the past 25 years the US government has engaged in a large expansion of the protection offered to the financial system: the counterparties of a “too big to fail” bank could expect to be repaid even if the bank failed and the Fed chairman himself had taken responsibility for handling systemic risks. Every bank was encouraged to focus only on its own profits. Monitoring counterparties’ balance sheets was unnecessary, as long as they were large, and, as for the financial system as a whole, that was the regulators’ problem.

Unfortunately in a free market economy, the strongest bulwark against systemic risk is the fact that firms want to protect themselves from bankruptcy. So, the losses from trading with counterparties that go bankrupt are minimised by shunning counterparties that have weak balance sheets. Similarly, if the firm sees systemic instabilities building up, it has an interest in bolstering its own capital position to weather the coming storm. By encouraging financial firms to ignore these risks, the government stripped the financial system of its most stabilising forces.

Therefore, the first question we should ask when reviewing the consequences of the crisis is: how has the US government performed in its new role as guarantor of the financial system?

Under the circumstances, it would be hard to give the regulators a passing grade. While some officials at the Fed and the Commodity Futures Trading Commission recognised the dangers of “too big to fail” banks, of the outsized risks taken on by Fannie Mae and Freddie Mac, of over-the-counter derivative markets, and of predatory subprime loans, these individuals were unable to generate a sense of urgency commensurate with the seriousness of the problems. The regulatory agencies had, in almost every case, been forewarned of disaster looming somewhere on the horizon; in every case they chose not to act.

This abject failure on the part regulators is a red flag; the recent transfer of responsibility for financial stability from the private sector to the central bank was a bad idea. The free market principles that held sway through the 19th and much of 20th century left individual financial firms with most of the responsibility for protecting themselves in a systemic crisis and encouraged them either to be well-capitalised or to risk failure.

The evidence indicates that the wholesale transfer of responsibility for systemic risk to the central bank has resulted in a financial system that is seriously undercapitalised. In a genuine free market system risk does not naturally flow to where it is least monitored and where capital requirements are lowest, because each firm protects its own balance sheet by trading only with counterparties that are well capitalised and competent risk managers.

How do we address the crisis, then? First, avoid being misled by Orwellian claims that turn the concept of a free market on its head and portray the banks’ mismanagement of risk as natural economic behaviour. It is government intervention in the form an excessively broad safety net for financial institutions that creates this behaviour. Second, recognise that the stability of the financial system requires a lender of last resort with very narrow responsibilities: it lends only to banks that play a role in the money supply and that have recently been approved by examiners as sound. The reason a central bank lends generously to banks in a crisis is not to protect the banks from failure, but to minimize the likelihood of a sudden decline the money supply. Third, recognise that the only way to shrink the mandate of the Fed is to make it possible for all firms to fail.

Congress needs to enact a resolution authority so that bankrupt financial institutions can fail without causing an implosion in derivative markets. The Fed was forced to take extraordinary action in 2008 to protect the stability of the money supply. This move was the unfortunate consequence of mistakes made in the 1980s and 1990s that allowed bad decisions to snowball by 2006 into a situation where credit default swaps and subprime mortgages began to serve, in part, as the collateral backing our money
supply. The challenge is to lay out a path from our profoundly destabilised financial system to a more solid system with more modest systemic guarantees where even “too big to fail” firms are allowed to fail.

Carolyn Sissoko was an adjunct professor of economics at Occidental College in Los Angeles and is currently writing a book on the financial crisis"

Me:

In my mind, the system of Implicit Government Guarantees to intervene in a Financial Crisis is the main cause of this crisis. However, it formed the basis of banking and investment for the last 25 years. It has produced major financial crises by wedding deregulation and guarantees, an unholy union. But everyone knows that the government will intervene to stop a panic or debt-deflation, or other large financial crises. Hence, there's no point in pretending that the opposite would be the case. Given that, we are left with guaranteeing and regulating.

Now, we can either guarantee banking and investment, as Gorton is advising, or split the two up.

Firstly:

"Bagehot's Principles":

1) If the Fed exists, it will be the Lender Of Last resort, and that has to be taken in to account in real world Political Economy. It should lend freely in a crisis to solvent banks.

2) The rules for LOLR( from here on down this includes any government guarantee ) intervention should be clear, public, and followed, otherwise Moral Hazard is ineffective. All guarantees must be explicit.

3) The terms must be onerous.
4) The LOLR should get something valuable in return.

Here are a few others:

5) The taxpayer's interests should come first.

6) Moral Hazard needs to be constantly applied by quickly liquidating problem banks in normal times.

7) Any entity receiving a guarantee will have to be supervised or regulated effectively, and violations should be quickly and severely punished.

8) There is no doubt that any entity receiving a LOLR guarantee will need to be more conservative in its practices in order to limit the liability of the taxpayer.

9) There should be a class of financial concerns that can act more freely, but they should not receive LOLR guarantees. They will be strictly supervised, which is preferable, or regulated though, and are subject to laws against fraud, etc. They should be self-insured.

Or:

Narrow/Limited Banking on the one hand, and a version of 9 above on the other hand.

I would like a system that has a firm and sound base, and, having that, allows another part of the financial universe to experiment and innovate, which will happen in any case. But not acknowledging the reality of the guarantees is what we previously had, and what we cannot allow to continue. We are learning the price of fooling ourselves with overblown views of our ability to stand firm on principle or ideology. When that does happen, it's more than likely to be in defense of a lost cause.
Posted by: Don the libertarian Democrat

But I think all we’ve done is replace an explicit guarantee with an implicit guarantee.

From the Baseline Scenario:

"Explicit and Implicit Guarantees

with 9 comments

Note: I wrote this post on May 18 but somehow forgot to publish it; I just found it in my drafts. It’s a bit out of date, but I think the point still stands.

I’m not sure if it’s official, but it’s been widely rumored that large banks that want to repay their TARP money will have to be able to sell new debt without the FDIC guarantee they got back in October. As a result, banks are falling over themselves with new, non-guaranteed debt offerings. The idea, I guess, is that banks that can raise money without the guarantee are showing that they are sound enough to operate without government support.

But I think all we’ve done is replace an explicit guarantee with an implicit guarantee. In October, no one was sure whether the U.S. government would bail out bank creditors in a pinch; after all, Lehman creditors got back less than 10 cents on the dollar, and AIG creditors took a big haircut because the Fed’s credit line came in senior to them. So the explicit guarantee was necessary for banks to issue debt.

Since then, however, the government has shown in many ways that it isn’t going to let major banks fail or force a restructuring (indeed, it insists that it can’t force a restructuring). The message of the stress tests, ultimately, was that Treasury is standing by to provide whatever capital is needed. In that situation, what risk do bank creditors face? Virtually none, except maybe political risk (the risk that the government’s policy will change). So the banks get to raise money without the stigma of a guarantee, they don’t have to pay a premium to the FDIC, then they get to pay back their TARP money, and the government can say that the banking sector is healthy. Everyone’s happy.

And if things go badly, the taxpayer is still there to make good on all those non-guaranteed bonds – at least for the banks that are, still, too big to fail.

By James Kwak"

Me:

Let’s look at China. China sold Agencies, Implicitly Guaranteed, and bought Treasuries, Explicitly Guaranteed. Now, they did this, apparently, after the way that Fannie/Freddie was bailed out, and Lehman was allowed to fail, and WaMu was seized. China immediately stated that they had previously believed that these implicit investments were really explicit. After they heard that we might haircut the bondholder’s of banks, they stated this point even louder, and threatened negative consequences.

My answer, and Geithner’s, was to guarantee everything. Explicitly. Now, were there any negative consequences to China’s shift from Agencies to Treasuries? In my opinion, there were. For one thing, it was part of a massive deflationary flight to safety that almost led to Debt-Deflation. Had that occurred, unemployment could have doubled, from these current levels. The point is that no one knows.

If the question is whether or not these banks are guaranteed, the answer is yes. See, we deregulated, but also guaranteed, these big banks. Does that remind you at all of the S & L Crisis, which was a bipartisan foul up, which is why it never really came up in the 1988 election. Neither party could get an advantage from the issue.

The Federal Government will never allow Debt-Deflation, or a serious threat of it. That reality, combined with the fact that we have a Lender of Last Resort, the Fed, and, now, the Treasury and FDIC as well, mean that we will always have guarantees going forward. The answer, then, needs to be regulation. Since I’m no big fan of regulators, I prefer Narrow/Limited Banking on the one hand, and an insured Investment Industry, on the other. Either self-insured, or by government. This part of my view is very close to Gorton’s view.

Without these kind of changes, we’ll be back here again soon. I’m sorry to have such a jaded view of regulators, but these foul ups just keep coming. Hence,although I used to favor Bagehot on Steroids, meaning a very tough regulator, I just can’t seem to believe in that possibility any longer.

Friday, May 29, 2009

Gorton’s solution to this problem is to involve the government in all manner of regulation — and insurance — of the securitization market

From Reuters:

"
Felix Salmon

nonrival, nonexcludable

May 29th, 2009

Why the government shouldn’t insure securitized assets

Posted by: Felix Salmon
Tags: economics

Ezra Klein does us all a favor this morning by spending 1,000 words or so summarizing a 20,000-word, 53-page paper by Yale’s Gary Gorton. Now to make it even shorter!

The key concept is the distinction between informationally-sensitive financial assets — assets which change in price when new information emerges — and informationally-insensitive financial assets — assets which don’t change in price when new information emerges. In the latter bucket we can include insured bank deposits, but bank deposits are insured only up to $250,000, and there are a lot of companies and other institutional investors who just want a safe place to park their cash and are also on the hunt for informationally-insensitive assets.

They found them — or thought they found them — in things like asset-backed commercial paper: they would hand over cash, and receive the senior tranches of securitized loans as collateral. When that happens, writes Gorton,

A ‘banking panic’ occurs when ‘informationally-insensitive’ debt becomes ‘informationally-sensitive’ due to a shock, in this case the shock to subprime mortgage values due to house prices falling.

Gorton’s solution to this problem is to involve the government in all manner of regulation — and insurance — of the securitization market, thereby making ABCP behave much like federally-insured bank deposits. I don’t like this solution at all, since it would send the contingent liabilities of the government into the stratosphere, and more importantly would ratify the demand for informationally-insensitive assets by creating trillions of dollars of new ones.

In my view of the crisis, it’s precisely the demand for informationally-insensitive assets which is the problem. And we need to get individuals, companies, and institutional investors out of the mindset that they can do an elegant little two-step around the inescapable fact that anybody with money to invest perforce must take a certain amount of risk. If you have a world where people are all looking for risk-free assets, you end up shunting all that risk into the tails. And the way to reduce tail risk is to get everybody to accept a small amount of risk on an everyday basis. We don’t need more informationally-insensitive assets, we need less of them."

Me:

I disagree. I did agree with almost all of Gorton’s views. For one thing, he agrees that we had, what I, in my sophisticated way, have been calling since September, a Calling Run, meant to connote a bank run like occurrence of getting to cash or safe investments. It’s been followed by a Proactivity Run and Savings Spree, thereby showing that my sophistication hasn’t increased.

The problem was Debt-Deflation or a Debt-Deflationary Spiral. I derived this view from Irving Fisher, assuming that, if he were alive, he’d acknowledge the parentage of my views. In any case, there are two solutions:

1) Bagehot’s Principles, meaning issuing a full government guarantee that necessitates, in order to work, an FDIC like agency that shuts down insolvent businesses without caring about their power or connections. This was my original view, and it’s like Gorton’s, and Felix dislikes it because of the guarantees.

Two points:

A: If you have a Lender of Last Resort, these guarantees might well be ineradicably implicit.
B: The point isn’t to have to spend the money, but simply allow enough confidence for a reasonable unwinding. Only a government has the resources for this, sad to say.

2) The other alternative is a split between Narrow/Limited Banking and Investment Concerns, which would be self-insured, while the Banks are government guaranteed, to the extent that they need to be.

Both are meant to stop major events like Calling Runs, not investors losing money. It seems to me that worrying about the particular investments verges on worrying about people losing money or trying to avoid recessions, which I consider impossible. We should focus on major events, not creating a perpetually spooked market.

I switched to Narrow Banking merely because I’ve experienced a crisis of faith in regulators as a class, although I agree that there are better and worse. I’m willing to become a believer again given a compelling scripture.

- Posted by Don the libertarian Democrat

Monday, May 25, 2009

backing debt with a guarantee does not require an immediate outlay of funds, the federal government could have to cover losses if there are defaults

TO BE NOTED: From the NY Times:

"
Localities Want U.S. To Support Muni Bonds

State and local governments are asking Washington to give them something that banks are trying to get rid of: federal bailout money.

California is asking that money from the Treasury’s TARP, the Troubled Asset Relief Program, be used to help back more than $13 billion in short-term borrowings. Members of Congress and several municipalities want bailout money to be used to cover more than $1 billion in losses from investments by municipalities in debt issued by Lehman Brothers, the investment bank that went bust.

And Representative Barney Frank, chairman of the House Financial Services Committee, is drafting legislation that would have the Federal Reserve, and potentially the Treasury’s bailout money as well, stand behind floating-rate municipal bonds — a $400 billion market that provides short-term financing to municipalities, but which has been largely frozen in the current credit crisis.

Another measure drafted by Mr. Frank, Democrat of Massachusetts, would create a public finance office within the Treasury Department to reinsure $50 billion in municipal bonds. This proposal comes as downgrades of municipal bond insurance companies have made it more difficult and costly for state and local governments to issue bonds.

All of the proposals are meant to help struggling state and local governments that are facing a cash-flow squeeze. The economic downturn has eaten into their tax bases as local businesses shut, houses are lost to foreclosure and there is a resistance to raising taxes. The risk to the federal government is that it could lose money if things get worse for municipalities and states. ( NB DON ) Although backing debt with a guarantee( NB DON ) does not require an immediate outlay of funds, the federal government could have to cover losses if there are defaults — which could be substantial if the economy weakens or states and municipalities cannot bring their budget deficits under control. Nonetheless, these overtures by state and local officials reflect a sense — perhaps just a hope — that municipalities suffering from a downturn in revenues and creditworthiness may find some relief in Washington beyond the stimulus money the federal government already is spending.

When the relief program was first conceived of last year, pleas by municipalities for a slice of the money went unheeded by Treasury officials who had earmarked the funds solely for troubled banks and financial institutions. But, in recent days, new conversations have taken place involving Federal Reserve and Treasury officials and state and local representatives that have given rise to cautious optimism.

“The municipal sector has been asking for federal assistance since TARP was just a glimmer in Hank Paulson’s eye,” said Matt Fabian, managing director at Municipal Market Advisors, an independent research firm. “But no one was pursuing it for months. Now, there has been a re-engagement in Washington about using the TARP money.”

Andrew Williams, a Treasury spokesman said, “We’ve had conversations with people from California and with people from around the country about the challenges facing the municipal market. And we continue to study the issue closely.”

In a speech last week at the National Press Club, Treasury Secretary Timothy F. Geithner said that the Treasury is “looking at ways to make sure these markets are working so that states and munis can meet their needs.”

But, according to a Bloomberg News account of the speech, Mr. Geithner cautioned: “I wouldn’t use the word bailout.”

With bailout fatigue setting in, it is unclear how successful the municipalities will be. At a Congressional hearing last Thursday called by Mr. Frank, federal officials remained cool to the idea of tapping into the relief fund, while still expressing concern over a credit squeeze facing many municipal borrowers.

David W. Wilcox, a deputy director at the Federal Reserve, said at the hearing that the Fed is “quite concerned” over any proposal that would extend federal guarantees to municipal debt. But, he allowed that if Congress does take that course, it should “tailor any government intervention in the municipal bond market relatively narrowly” and provide for a quick government exit when market conditions improve.

On the same day, Mr. Geithner told a House Appropriations subcommittee that the relief money cannot be used to resolve local government budget crises, since that money has been reserved for financial companies.

He said, however, that the Treasury would work with Congress to help states like California, which have been struggling to arrange backing for municipal bonds and short-term debt. Mr. Geithner did not provide any specifics.

Clearly, market conditions are not favorable in several corners of the municipal bond market, which consists of more than 50,000 public entities that have issued about $2.7 trillion in debt.

In April, Moody’s Investors Service issued its first-ever blanket report on municipalities and assigned a negative outlook on the creditworthiness of all local governments in the United States. This suggests that Moody’s may downgrade the ratings of many municipal issuers, which would increase their borrowing costs.

The biggest squeeze right now is on variable-rate demand notes, a common form of floating-rate borrowing that is backed by the promise of having sufficient future municipal revenues to repay investors — an increasingly uncertain proposition. The relief money would be used to guarantee these notes.

California, which has been crying the loudest for relief money, is in worse shape than most municipal borrowers. In a May 13 letter to Mr. Geithner, California’s treasurer, Bill Lockyer, said that the state “will be almost out of cash in July.”

Mr. Lockyer added that it is “highly unlikely that the state can access the short-term market ... based on its own credit.”

“We believe that California is not the only state to confront the same short-term cash-flow borrowing needs,” said Tom Dresslar, a spokesman for the California treasurer’s office. “But no one has as great a need as we do in terms of dollars.”

Michael Decker, a co-chief executive for the Regional Bond Dealers Association, concurred.

“All kinds of municipal borrowers are facing revenue shortfalls,” said Mr. Decker. “California is the largest example. Some states are better off than others. But all outstanding debt is backed by tax revenues. And municipalities are facing a greater or lesser level of distress.”

Also clamoring for help is a group of municipalities that purchased Lehman debt, which is now nearly worthless. Legislation authorizing the use of relief money to make these purchases was introduced by two California Democratic representatives, Jackie Speier and Anna Eshoo. If approved, this would be more like a bailout than a guarantee, because the federal government would be paying face value for debt that otherwise has little value.

The price tag on that proposal is around $1.6 billion. The argument promoted by the two congresswomen is that the Treasury and Fed allowed Lehman to fail, causing governmental bodies to lose money.

Though this effort has hit stiff opposition, Ms. Eshoo has not given up.

“It’s been said that some banks are too big to fail,” Ms. Eshoo said in testimony at a May 5 hearing held by Mr. Frank on the issue. “It can also be that counties, school districts and cities are too small to be noticed.”

Thursday, May 21, 2009

At least those that are not guaranteed by the FDIC.

From Follow The Money:

"China’s new barbell portfolio: Treasuries and commodities?

Keith Bradsher’s New York Times story on the recent evolution of China’s foreign portfolio gets — at least in my view — the story right. Of course, that may be because I was — rather obviously — a source for the story. Check out the charts that accompany the article!

The basic story of China’s foreign portfolio is simple: it is trying to reduce the amount of (credit) risk in its fixed income portfolio while simultaneously taking on more commodity risk.

China’s purchases of Treasuries (especially short-term bills) have gone up even as China’s reserve growth has slowed, as China shifted money out of Agencies and — in all probability — out of money market funds that are taking credit risk and other privately managed accounts. The failure of Reserve Primary had a big impact on China. Bradsher:

“Financial statistics released by both countries in recent days show that China paradoxically stepped up its lending to the American government over the winter even as it virtually stopped putting fresh money into dollars. This combination is possible because China has been exchanging one dollar-denominated asset for another — selling the debt of government-sponsored enterprises like Fannie Mae and Freddie Mac in a hurry to buy Treasuries. ….

China was the world’s biggest buyer of [securities issued by government-sponsored enterprises] a year ago, splashing out more than $10 billion a month. But in the 12 months through March, it actually had net sales of $7 billion, and ramped up purchases of Treasuries instead. China has also changed which Treasuries it buys. It has done so in ways calculated to reduce its exposure to inflation or other problems in the United States. As recently as a year ago, China actively bought long-dated bonds, seeking the extra yield they could bring compared to Treasury securities with short maturities, of which China bought virtually none. But in each month since November, China has been buying more Treasury bills, with a maturity of a year or less, than Treasuries with longer maturities. This gives China the option of cashing out its positions in a hurry, by not rolling over its investments into new Treasury bills as they come due should inflation in the United States start rising and make Treasury securities less attractive.

At the same time, China has sought to ramp up its exposure to commodities. China’s government clearly is adding to its strategic stockpiles — and perhaps encouraging state firms to build up inventory as well. China’s government is encouraging Chinese state firms to invest more abroad, especially in the mining sector. And China’s government is providing financing to cash-strapped commodity exporters (Russia, Kazakhstan, Brazil and no doubt others) to help tide them through a rough patch and, China hopes, to secure future supplies. Bradsher:

“This spring China has also been stepping up its purchases of commodities, which are usually bought in dollars. Iron ore has been piling up on Chinese docks, government stockpiles of crude oil and grain are being expanded and stockpiles are being started for products like gasoline, diesel and sugar.”

China’s government presumably likes commodities in part because it believes in its own story — and, if you are bullish on China, conventional wisdom holds that you also should be bullish on commodities. China also hopes that its investments abroad will help to assure it a secure supply of the raw materials it needs. At the most basic level, the more investment in commodity production now, the lower the future price — and as a commodity importer, China would benefit from lower prices. And China could well view commodities as an inflation hedge.

That said, commodity price are volatile — so holding commodities is not devoid of risk. Buying the equity of commodity producers can be equally risky. And there is a long history that shows that investing in mineral production abroad is risky.

These though are risks that China seems to want to take right now.

Conversely, China doesn’t seem keen to take risk in the fixed income market. The old game of buying Agencies to get a bit more yield than Treasuries offer is over. And, I would guess — based on China’s comments about the importance of protecting the value of China’s investment in the US — that China also isn’t all that keen on the long-term bonds of large financial institutions. At least those that are not guaranteed by the FDIC.

China though doesn’t seem to have found a way to reduce its currency risk, despite all the recent talk. Probably because it is hard for a large country that pegs its currency tightly to the dollar to do so. China — per Bradsher — has found that it cannot buy gold without moving the market. That applies to currencies too.

Best that I can tell — see Figure 7 of the latest Setser/ Pandey paper on the management of China’s foreign portfolio — the United States’ share of China’s total portfolio has been fairly constant. The US data on its own suggests that China was moving out of dollars from mid-07 to mid-08,* and then moved back into dollars last fall. My best guess though is that the US data overstates both the move out of dollars from mid-07 to mid-08 and the move back into dollars in the fall. Rather than moving out of the dollar, China was moving out of Treasuries — and increasingly holding dollars in ways that the US data doesn’t pick up. Call it reaching for yield. After the crisis, China moved back into Treasuries — and started holding more of its dollars in ways captured by the US data. That at least is my best guess.

One thing to watch going forward: what China does if its reserve growth picks up again, and it has to put more money to work. For the past six months, China has essentially been reallocating its existing portfolio. Given China’s still large current account surplus, that was only possible because private money was leaving China. But if China ends up recovering faster than the rest of the world, capital inflows to China could easily resume … pushing China’s reserves back up.

* China’s recorded purchases of US assets from mid-07 to mid 08 are inferred primarily from the survey data. And the increase in China’s stock of Treasuries and Agencies was lower than I would have anticipated given the overall increase in China’s foreign assets. This period was also marked by large institutional changes in the way China manages its reserves - changes that potentially meant that the US data missed some of China’s holdings. For example, the CIC’s large holdings of dollar-denominated money market funds also did not appear in the survey data — likely because the CIC invested in “offshore” funds. Greater use of private managers and managed accounts will tend to lower recorded US holdings as well. There is also some uncertainty about the total scale of China’s foreign portfolio — which has an impact on the calculation of the United States share of the portfolio. I have compared China’s US holdings to its total foreign portfolio, not just to its reserves. That means that I am including the CIC and the PBoC’s other foreign assets and a (complicated) measure of the state banks foreign portfolio alongside China’s reserves."

Me:


  1. “Conversely, China doesn’t seem keen to take risk in the fixed income market. The old game of buying Agencies to get a bit more yield than Treasuries offer is over. And, I would guess — based on China’s comments about the importance of protecting the value of China’s investment in the US — that China also isn’t all that keen on the long-term bonds of large financial institutions. At least those that are not guaranteed by the FDIC.”

    I’m still waiting for a good explanation of this. Even on the bonds of large financial institutions, it seems to me that the US didn’t like the idea of giving a big haircut to China.

    Unlike most people, I find the Chinese explanations for their actions, especially on their website, to make sense and appear forward looking, especially when you set them up against most other governments in this crisis.


  1. don — you are right. the us didn’t want to do anything dramatic that china would consider an affront. like default on agencies.

    but the us didn’t protect reserve primary (which china had invested in) from the fall out of LEH, and i would be quite surprised if SAFE didn’t hold some LEH and AIG bonds (LEH bonds weren’t made whole, obviously). The total amounts involved were small, but china in the crisis discovered that it is fundamentally loss adverse and the us gov didn’t protect it from all credit losses.

    and then there is a rumor (unconfirmed) that china (via SAFE) may have had some of the agencies preferred stock (or something in the capital structure between debt and equity) and was surprised when that wasn’t protected. just a rumor tho.

    as far as i know SAFE has never tried to explain in public why it shifted into agencies or why it shifted out … nor has it said anything in public about its little foray into equities. so i guess I am a bit less impressed by china’s public policy statements than you are!

Sunday, May 17, 2009

To us, that week, it looked very much like a run on the entire financial system

TO BE NOTED:

Sunday, May 17, 2009

How TARP Began: An Exclusive Inside View

May 14, 2009 04:01 PM ET | Rick Newman | Permanent Link | Print

When it first came into existence last September, TARP—the troubled assets relief program—sounded like just another ungainly government acronym. But since then, it has become an integral—and controversial—part of America's recession economy.

TARP's chief architect was Henry "Hank" Paulson, President Bush's treasury secretary, who led the financial rescue along with Federal Reserve Chairman Ben Bernanke and New York Fed Chairman Tim Geithner, who's now Paulson's replacement at treasury. Their initial plan was to use the $700 billion in TARP funding approved by Congress last October to purge financial firms of their so-called toxic assets.

[See why the banks still aren't fixed.]

But TARP morphed into an über-bailout that included direct cash injections into banks, the auto rescue, the AIG intervention, and other government efforts to revive the economy. If it sounds like a trial-and-error experiment, well, that's how it felt to the policymakers who designed it, too. "When we looked for easy solutions, we kept coming up empty," says David Nason, who was a senior Treasury Department official during the Bush administration. "Hank used to say all the time, 'We're going to have to do this with duct tape and fishing wire.' "

Nason and some of his Treasury colleagues did much of the jury-rigging, running doomsday scenarios, negotiating emergency deals with banks, wooing incredulous members of Congress, and devising ways to deal with problems once considered unthinkable. Frustrated Treasury Department officials, for instance, foresaw much of the carnage but found themselves poorly equipped to stop it. Anxious finance ministers from around the world began calling Treasury last summer to find out what the government planned to do about the developing crisis. The most tense moment may have been the September failure of Lehman Brothers, which occurred with alarming speed after British financial regulators scotched a takeover bid by the British bank Barclays.

[See 6 surprises from the recent bank stress tests.]

Nason and two other former Treasury officials, Philip Swagel and Kevin Fromer, spoke recently at a panel discussion sponsored by the Milken Institute. Their remarks form one of the most thorough accounts to date of how the government struggled to contain the worst financial crisis since the Great Depression. (See a video of the full discussion, which I moderated.) Here's a condensed version of their remarks:

David Nason, former assistant treasury secretary for financial institutions: The first inflection point was March 16, 2008, which was the acquisition date by JPMorgan Chase of Bear Stearns. The sheer time it took for this institution to go from viable to nonviable was breathtaking. Just two days before, the regulator [the Securities and Exchange Commission] had said Bear had adequate liquidity of $8 billion. This is an important inflection point because it was the first time the government had stood up and said we are going to support nonbanking institutions. We knew at that point the times had changed. We knew the policy ramifications were going to be very difficult and far reaching.

[See 5 signs the bailouts are getting better.]

We worried most significantly about the consequences of other similarly situated firms. It was a very trying and stressful time because when we looked for easy solutions, we kept coming up empty. The government did not have a ready-access pool of money to support or manage the resolution of financial institutions. The political climate was very challenging—at the time, people saw this as a bailout for fat cats on Wall Street. And there was some jurisdictional squabbling in Washington.

Philip Swagel, former assistant treasury secretary for economic policy: Right after Bear failed, the economy looked like it was actually in pretty good shape considering the problems in housing and the financial sector. Overall growth was positive, driven especially by exports. In the wake of Bear's failure, we looked at options, including many things that are now familiar: buying assets, insuring assets, buying pieces of pieces of institutions, in other words injecting capital, and a massive bailout from the bottom from refinancing every troubled homeowner. And we said those are all things you could write down, but back then, you had rebate checks that had been enacted but weren't yet going out, and we had positive growth. It would have been hard to imagine getting the authority to do those things or the approval from Congress for a contingency fund in case things got worse.

Nason: The next inflection point was July 2008. The government was worried about the big investment banks, CDS [credit-default-swap] spreads were blowing out, we were also worried about Fannie Mae and Freddie Mac. These were some of the most leveraged institutions on Earth. Together, they had over $5 trillion in exposure if you consider the guarantee obligations that they had. Match that against about $60 billion in capital. We were also concerned that the housing correction was turning out to be significantly worse than the GSEs [government-sponsored enterprises, such as Fannie and Freddie] expected. We were very concerned that the GSEs were being overly optimistic about their ability to manage risk and withstand future losses.

[See the best and worst bailed-out banks.]

The GSE equity prices were getting punished during this time. More important to us, however, was the debt market. It was very clear to us there's no way the U.S. financial system is going to allow a firm the size of Fannie Mae to collapse( NB DON ). We were very worried about the trillions in debt they had outstanding, and what it would do to confidence if we let that debt go.

At this time, the Treasury was getting calls from finance ministers' offices from different parts of the world inquiring, "What is the government's relationship with Fannie Mae and Freddie Mac?" It's odd, but this appeared to be the first time that people were focusing on the fact that these are quasi-governmental institutions.

During this time period, the home loan banks, another GSE with similar exposure to the housing market, decided to postpone an auction. Every auction was something that we focused on and were worried about.

[See the banks most likely to pay back their bailout funds.]

We made the decision based on this set of circumstances that we had to support the GSEs. How were we going to do that? What did we have in our toolbox? Essentially nothing. We had about $2 billion of backup credit support for the GSEs. For $1.4 trillion organizations. This was clearly not enough to support these institutions in any real way. And we had no ability to provide any kind of equity support at all. So we decided we had to go up to Congress, bite the bullet, and ask for authority to backstop these institutions.

On July 30, 2008, the president signed a bill into law to provide equity support to these institutions. And we had the ability to support their debt up to the federal debt limit.

We made the judgment not to request the authority to nationalize the GSEs. It would have muddied the political discussion. I'm not sure we would have gotten the authority, and at this time, there wasn't a pressing need to do so. There's a long, tortured story about how the GSEs and Washington interface. But we wanted to have broad authority to support the GSEs and prevent their collapse.

[See why the auto bailout is a good model for other struggling firms.]

The entire month of September was an inflection point under my definition. But the first inflection point associated with September is Sept. 7, 2008, when the GSEs were forced into conservatorship. That came after regulators determined that they were drastically undercapitalized.

Two days later, AIG's stock fell 19 percent. Lehman's discussions to sell itself to the Korean Development Bank failed. The next day, Lehman put itself on the market for sale, with no clear takers. After some very tense discussions about whether there would be a purchaser, like JPMorgan was for Bear Stearns, we were very distressed to know that there were no takers.

So from the 10th to the 14th, the Federal Reserve, with the Treasury's support, decided to flush the system with liquidity. The Federal Reserve expanded the level of collateral the primary dealer credit facility would take, they increased the collateral that the term securities lending facility could take, and they increased the ability of banks to support nonbanking institutions. The government was putting "foam on the runway" to try to deal with what we were afraid of, which was how the market would react to a Lehman Brothers bankruptcy.

The next day, Lehman Brothers filed for bankruptcy.

The question is: Did we let Lehman Brothers fail? That assumes it was a choice that we made. The simple truth is that the government was presented with an institution with a $600 billion balance sheet, with enormous leverage. Confidence in the institution was virtually nonexistent. The only way to stabilize a firm under these circumstances is to stop a run on the institution, stop counterparties from claiming their debts should immediately come due. That was manageable in the Bear Stearns situation because someone was willing to guarantee all or most of those liabilities.

[See how bailouts can butcher capitalism.]

The public posture was that government support would not be available. But there wasn't a single credible buyer at the table who was turned away by us.

So when people ask, "Why did you let Lehman Brothers fail?" I ask, "What is the deal that the government turned down that would have prevented Lehman's failure?" If there's not someone willing to take on a balance sheet as large as that of Lehman Brothers, what is the government to do? The government has a few options: We have a lending facility at the Fed, you could provide a loan to them secured against collateral, or you could guarantee all their liabilities. That might have been the right decision, but we had no authority to do that before TARP.( NB DON )

Looking back, if we could have plugged some of the holes in our authorities, maybe this could have been done differently. I don't think we would have gotten those authorities if we had asked for them before September.

[See why the feds rescue banks, not homeowners.]

Of course, things continued to be unpredictable. We didn't predict that the U.K. bankruptcy process would essentially destroy all confidence in that funding model and that business model. And we didn't expect that the commercial paper market would essentially shut down because Lehman Brothers' commercial paper was impaired. Those two markets were the transmission vehicles that killed confidence, which we didn't expect.

That same day as Lehman, Bank of America acquired Merrill Lynch. We didn't have a second to catch our breath. The day after the Lehman bankruptcy, AIG got a $50 billion loan from the Federal Reserve. There was no significant discussion over whether the Federal Reserve was going to provide backup facilities to AIG because of two distinguishing characteristics: One, they were huge. They were global. They were bigger than Lehman Brothers. But the more important distinction is that the Fed is in the business of providing loans when it is "secured to its satisfaction." And AIG had the benefit of having solvent, highly regulated, very valuable insurance subsidiaries to which the Federal Reserve felt comfortable extending its loan facilities.

[See more companies likely to fail this year.]

After that we get to Sept. 17 2008, which was essentially the creation of the TARP concept. It was at that point that there was a meeting of the minds between Paulson, Bernanke, and Geithner that enough is enough, we're going to break the back of this crisis, and we're tired of not having the tools to deal with this crisis. And the judgment was made that we were going to ask for broad authority from Congress.

At that point, it was essentially 24-hour duty at the Treasury Department. Some people slept there.

Kevin Fromer, former assistant treasury secretary for legislative a ffairs: For context, this was a program about the size of the entire federal operating budget on an annual basis. Congress usually works through that process for 10 or 15 months, just to keep the lights on. We were asking Congress for $700 billion in basically a week or two. In the context of a national election. An election year is typically not the year to do big things.

We had one week left in the legislative calendar. It was not possible to do it in a week. I wasn't sure it was possible to do it at all. We needed to get somewhere fast, so we sent up the infamous three-page bill, which was draft legislative text the committees needed to start the discussions.

[See why the markets hate the idea of bank nationalization.]

Swagel: It was very difficult to say, if this shock happens, you will get this economic effect. In September, the nation as a whole didn't understand that what was happening in the credit markets would matter to them. There was this sort of Wall Street-Main Street divide. It was hard to explain to people why this mattered.

The week of Lehman and AIG, there was a panicked flight from mutual funds, and that led to a lockup in commercial paper. In our view, that was really the key, the CP market breaking down. That had a direct link to investment. Businesses use that to fund their daily operations. That would lead to a direct plunge in business spending, and that's exactly what we've seen over the last two quarters. A very sharp decline in business investment.

The one-month Libor [London interbank offered rate] spread is a measure of stress in bank lending. It's really, do you trust a bank to hold your money for a month. After that week, the stresses in the bank funding markets were huge. To us, that week, it looked very much like a run on the entire financial system. ( NB DON )

Nason: We were afraid of a complete and utter collapse of the global financial system.( NB DON )

Swagel: Imagine if the Fortune 500, blue-chip companies, can't buy paper clips or meet their payroll. All the things these firms rely on money-market funds and commercial paper for. And it goes downhill from there. It starts with the big firms and then every firm in the nation.

Fromer: This was an extremely difficult communications challenge. It made it enormously difficult to sell the package to Congress and for them to sell it back home. They were angry when they came back from home after the election. They had seen the amount of money they were being asked to put into institutions, getting anecdotal information from small businesses and lending institutions, and the picture was, we've invested significantly in these institutions, and we're not seeing credit flow to consumers and small businesses.

The markets were volatile for quite some time, and people became desensitized to volatility in the markets. What people didn't understand, which was quite reasonable, was the credit markets, how credit is provided in this country. That's not a criticism; it's arcane to anybody without a certain educational background. It's an almost-impossible-to-explain set of circumstances.

Nason: People were getting used to seeing the stock market go up and down. We were trying to explain, "What's happening in the equity market is not really what we're worried about. We're worried about some other market that you've never seen and aren't familiar with," and people look at you like you're insane because you're asking for $700 billion and you can't provide anything besides a chart to show why it's important.

[Here's the chart, which shows how rapidly widening credit spreads reflect a seizure in the credit markets.]

People could appreciate the money-market mutual funds situation. There is $3.3 trillion of money invested in money-market mutual funds. A panic in these funds helped in terms of selling the importance of our message. And the commercial-paper market stress was important in communicating this as well. If that market collapses, you could have huge employers saying, I'm going to start laying people off. I'm going to start shutting plants down, I'm going to start defaulting on my bonds, and that's going to trigger bankruptcy( NB DON ). Those are the kinds of things you had to say, in the doomsday scenario, to convince people that this was critical to the system.

After [the first TARP vote] failed in the House [on September 29], then the equity markets finally responded. [The Dow Jones industrial average plunged 778 points.]

Fromer: It was clearly a response that forced a number of people to say, "OK, we get it now."

Swagel: Even after the legislation passed, stresses in bank funding still got worse. So we got what we needed; we were thinking about buying assets, but we needed to think more broadly.

Nason: There were two purposes at the time. This is a critically important point and something the current administration is suffering under. The dual purposes were financial system stability and provision of credit to the economy. People are not focused at all on the fact that the former is the primary reason we went up and asked for emergency authority. To derail a total breakdown of the financial markets and the global financial system. And we believe and hope that the confluence of programs put into place in a very short period of time actually did that.

The second part of it is, getting credit flowing into the economy. People seem to only focus on, "Why isn't this money being put into the economy?" That's important, of course, but you have to remember a significant portion of this money was there to be a buffer against future losses.

Swagel: To me, the stabilization of the financial markets is the salient accomplishment of the TARP and the actions of the Treasury in the fall. The normal playbook for dealing with a bank crisis is first, winnow out the banking sector so the zombie institutions don't clog up the credit channels and divert resources. As a society, I'm not sure we're going to do that. Next is stabilize, inject capital into the firms that are left so they're still viable. And No. 3 is do something about the balance sheets. Give certainty about the performance of the assets and the viability of the firms. I think we did No. 2, we stabilized the system. No. 3 is still the ongoing challenge.

Nason: The reason the TARP morphed from asset purchases to injecting capital is really quite practical. Asset purchases were taking longer than we had hoped, and it was more complicated with the vendors. Also, we needed to be in lockstep with our brethren around the world. The U.K., France, and Germany were prepared to guarantee the liabilities of the banking sector and were going to deploy capital into their banks.

Fromer: The folks in place right now clearly have the advantage of looking back at what we did and the conditions that existed when we did it. They're benefiting from experience. A number of them were part of the process going back to last summer.

Swagel: The job of the TARP has not been done, but the first step is done. In terms of the larger picture of what matters to families, we're still pretty far away from getting back to normal.

Nason: There are still valuation problems with a lot of the assets on bank balance sheets. Then we still have to deal with inevitable credit contraction.

Fromer: It's not conceivable to me that there's a TARP II. It's going to take time for these programs to stand up and operate and invoke full participation from all quarters. Given dynamics right now, I think it's unlikely there will be another TARP."